Fight BusinessData
The pay-per-view ceiling: what the biggest reported US buy rates tell us
Only two fights are reported to have passed 4m US pay-per-view buys, and Floyd Mayweather headlined both. We map the ceiling and what it takes to reach it.
Imogen Clarke
6 min readFigures as of 20 October 2026
Key facts
- Highest reported US buys
- 4.6m
- Mayweather v Pacquiao, 2015 (reported)
- Second highest
- 4.3m
- Mayweather v McGregor, 2017 (reported)
- Biggest MMA event
- 2.4m
- Khabib v McGregor, UFC 229, 2018 (reported)
- Mayweather's share of our list
- 60%
- 11.3m of 18.9m reported buys across seven fights
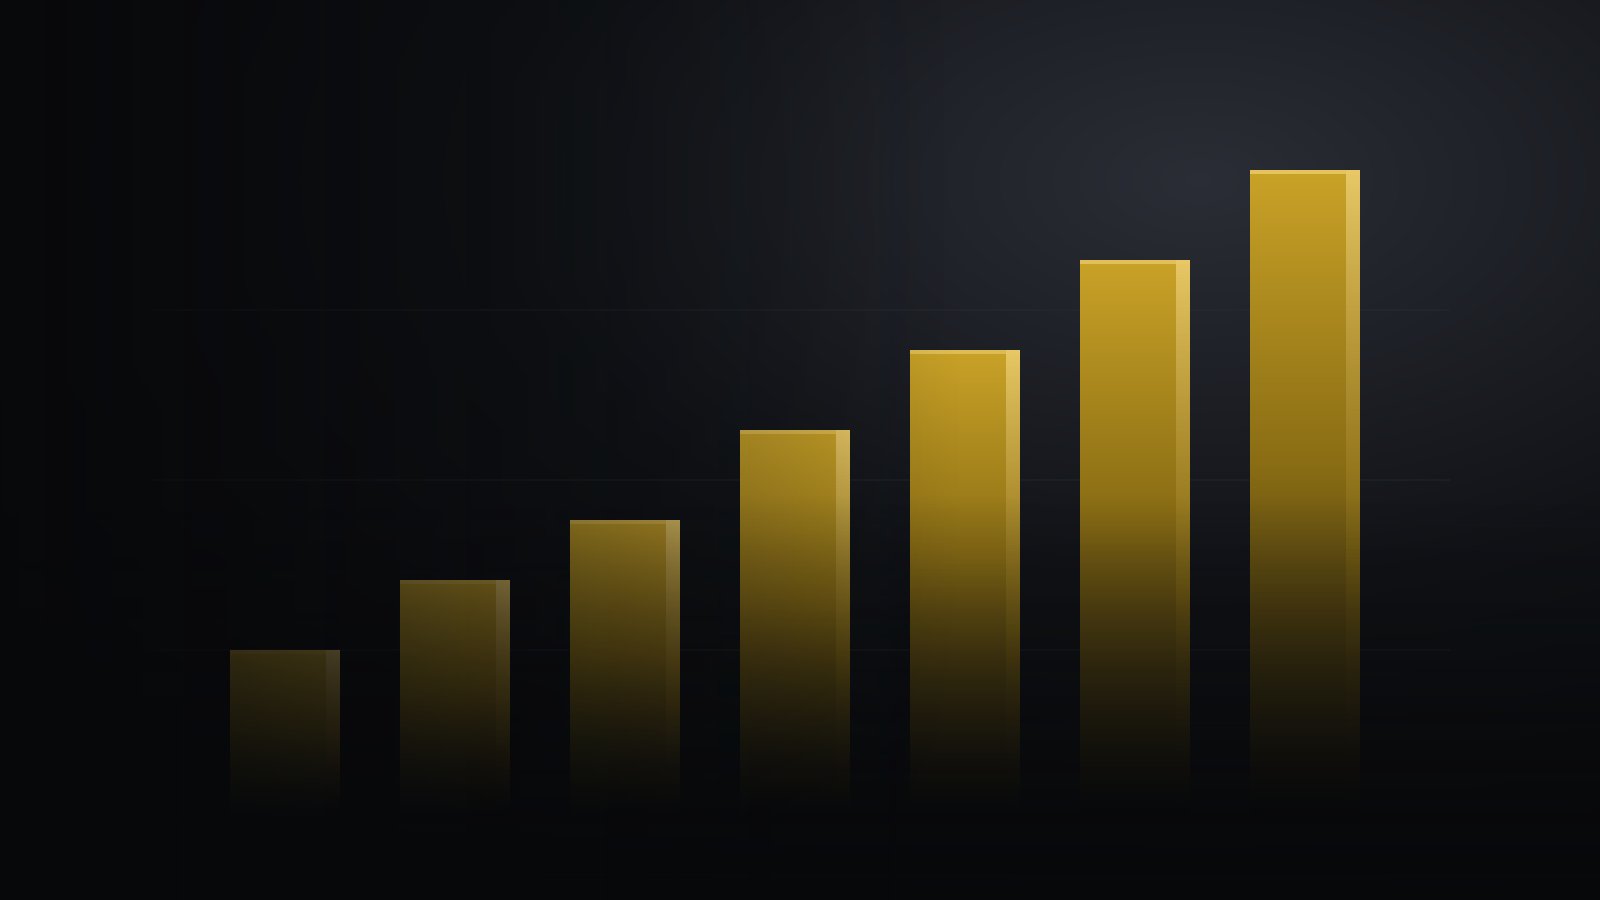
Only two combat-sports events are reported to have passed four million US pay-per-view buys: Floyd Mayweather against Manny Pacquiao in 2015, at about 4.6 million, and Mayweather against Conor McGregor in 2017, at about 4.3 million. Below them sits a gap of nearly two million buys before the next tier begins. That gap is the pay-per-view ceiling, and studying the handful of fights that reached it says a great deal about what fight fans will actually pay for.
A buy rate — the number of households that paid for a pay-per-view broadcast — is the fight business's headline commercial number. It is also a figure that comes, almost always, from the promoter or the broadcaster rather than an audited filing. Every number in this piece is therefore a reported figure: the one announced or widely reported at the time. They are US buys only, they are not adjusted for price, and they are rounded.
The reported numbers
We have taken seven of the most widely reported US buy rates in boxing and MMA history. This is not a complete league table, and the precise figures were sometimes revised or disputed after release. But each of these numbers has been reported consistently enough that we are comfortable using it.
| Fight | Year | Sport | Reported US buys |
|---|---|---|---|
| Mayweather v Pacquiao | 2015 | Boxing | 4.6m |
| Mayweather v McGregor | 2017 | Boxing | 4.3m |
| Mayweather v De La Hoya | 2007 | Boxing | 2.4m |
| Khabib Nurmagomedov v McGregor (UFC 229) | 2018 | MMA | 2.4m |
| Tyson v Holyfield II | 1997 | Boxing | 1.99m |
| Lewis v Tyson | 2002 | Boxing | 1.97m |
| Pacquiao v De La Hoya | 2008 | Boxing | 1.25m |
| Mayweather v Pacquiao (2015) | 4.6m |
|---|---|
| Mayweather v McGregor (2017) | 4.3m |
| Mayweather v De La Hoya (2007) | 2.4m |
| Khabib v McGregor, UFC 229 (2018) | 2.4m |
| Tyson v Holyfield II (1997) | 1.99m |
| Lewis v Tyson (2002) | 1.97m |
| Pacquiao v De La Hoya (2008) | 1.25m |
Source: Promoter and broadcaster figures as reported at the time
Three tiers stand out. At the top, two events above four million. In the middle, four events clustered between roughly 1.97 million and 2.4 million, spread across more than two decades. Below that, events like Pacquiao against De La Hoya, enormous by any normal standard but well short of the peak. The middle cluster is the striking part: across 1997, 2002, 2007 and 2018, very different fights in a very different media landscape all landed within about 0.4 million buys of each other. That looks less like coincidence and more like a natural limit for a huge fight that has not broken out of its core audience.
What breaks the ceiling
If two million is roughly where the biggest fights for fight fans top out, the two events above four million had to recruit people who do not normally buy fights. Looking at the list, we see three ingredients.
Crossover star power. Mayweather headlines both four-million events. By 2015 he was not only an unbeaten champion but a mainstream celebrity, as recognisable to casual viewers as to boxing fans. Pacquiao brought a global following and a story of his own. When both sides of a bill can sell to non-fans, the audience multiplies rather than adds.
Two-sport curiosity. Mayweather against McGregor was not a conventional boxing match. It put the UFC's biggest star into a boxing ring against the sport's most famous defensive fighter. Plenty of viewers bought it to settle an argument rather than to watch elite boxing. Curiosity is a powerful seller, and it is one of the few things that can bring two separate fan bases to the same screen.
A long rivalry build. Mayweather and Pacquiao were discussed as an inevitable matchup for roughly five years before they met. Tyson and Holyfield had a first fight in 1996 to build on. Khabib and McGregor had a personal feud that played out publicly well before UFC 229. Every one of the top events had a story the public already knew before the fight was signed.
The ceiling is not set by how good the fight is. It is set by how many people who never buy fights decide this one is worth it.
Notice what is missing from that list: competitive quality. Several of these fights were one-sided, and that did nothing to reduce the buys, because the money had already been spent before the first bell.
A business built on a few names
The concentration in these numbers is extreme. Our seven fights total about 18.9 million reported buys. The three involving Mayweather account for 11.3 million of them, or roughly 60%. Add McGregor's UFC 229 and two men account for 13.7 million buys, about 72% of the list.
Only eight fighters appear across all seven events. Mayweather appears three times; McGregor, Pacquiao, Tyson and De La Hoya twice each.
| Name | Appearances in our list | Combined reported buys |
|---|---|---|
| Mayweather | 3 | 11.3m |
| McGregor | 2 | 6.7m |
| Pacquiao | 2 | 5.85m |
| Tyson | 2 | 3.96m |
| De La Hoya | 2 | 3.65m |
These totals overlap, because several fights involve two names from the table, so they cannot be added together. But they make the point. The business of the biggest pay-per-views has historically rested on a very small number of fighters, and when one of them retires, there is no guarantee that anyone takes over the slot. For a promoter, that concentration is both the prize and the risk: one superstar can carry a company's year, and the same superstar's absence can leave a hole that no amount of depth on the undercard can fill.
Why the comparison keeps getting harder
These figures span 1997 to 2018, and comparing them directly comes with three health warnings.
Prices changed. The figures are nominal, and the cost of a buy rose sharply across the period. Mayweather against Pacquiao carried a reported US price of about $100 for the high-definition broadcast, far above the typical price in the late 1990s. A buy in 2015 represented a bigger spend than a buy in 1997, so equal buy counts do not mean equal revenue, and revenue figures adjusted for inflation would tell a different story again.
Households and access changed. Pay-per-view in 1997 depended largely on cable and satellite boxes. By the 2010s, buys also came through apps and online streams. A buy also counts households, not viewers, and public screenings in bars and venues are counted differently again.
Distribution models changed. Since 2018, the biggest shift has been the move of fight sports onto streaming platforms and global services. Some major events are now sold on a subscription service, some through app-based pay-per-view, and some through worldwide platforms that report global rather than US figures, if they report a number at all. Where a broadcaster folds events into a subscription, there may be no buy rate to compare. A modern event could reach a vast audience without ever producing a number that sits comfortably on this chart.
That makes the historical list more valuable, not less. It is a record of what the traditional US pay-per-view model could do at its peak, under rules that no longer apply in the same way. When a modern figure is reported, we would want to know which country it covers, which platform it counts, and whether it measures buys, subscribers or viewers before putting it alongside 4.6 million.
The ceiling, read plainly
The reported data tells a consistent story. The biggest fights for fight fans have tended to stall around two million US buys. Breaking far beyond that has required a crossover star, a story the public already knows, and usually a hook that drags in people who do not follow the sport. Only Mayweather has done it twice, and every top event has depended on a very small cast. As distribution moves to streaming and global platforms, the old buy-rate scoreboard is becoming harder to update, which means the 4.6 million mark may stand less as a record to be broken than as the high-water line of a model that has already changed.